
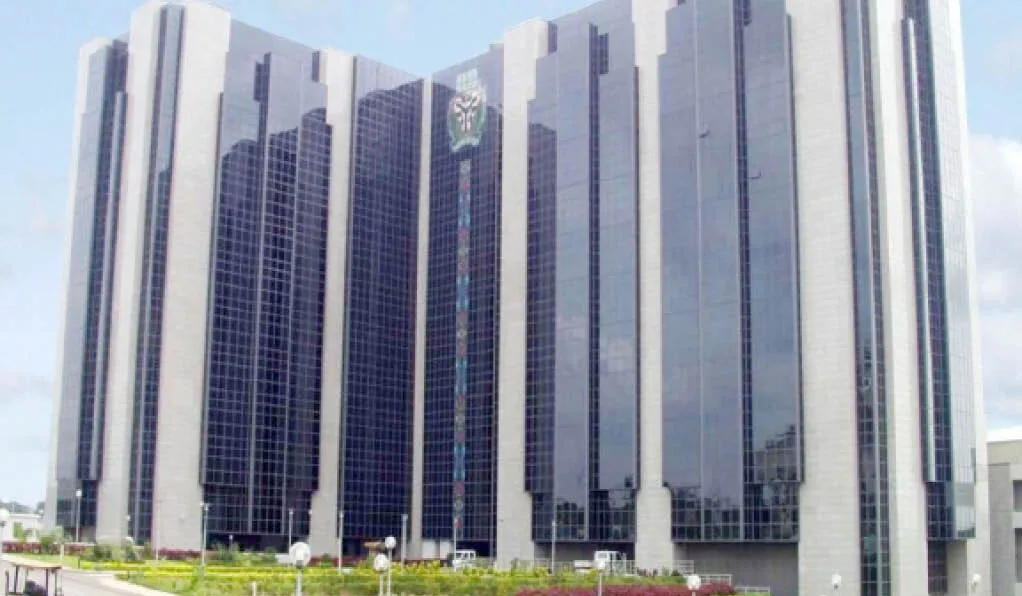
ABUJA:The Central Bank of Nigeria (CBN) has cut its Monetary Policy Rate (MPR) from 26.5 per cent to 23 per cent, in a major shift that could affect borrowing costs, business investment, bank lending and economic growth.
The decision was announced after the Monetary Policy Committee (MPC) concluded its two-day 307th meeting in Abuja on Tuesday, September 22, 2026.
The 350-basis-point reduction has triggered mixed reactions among economists and financial analysts, with some describing it as a timely move to support businesses and economic activity, while others have questioned the scale and likely impact of the decision.
The Chief Executive Officer of the Centre for the Promotion of Private Enterprise (CPPE), Dr Muda Yusuf, said the size of the adjustment was largely unexpected but represented a significant departure from the prolonged restrictive monetary policy environment.
CBN Governor Olayemi Cardoso said the MPC decided to reset the MPR and recalibrate the policy corridor to strengthen monetary policy transmission and reinforce the importance of the benchmark rate.
The committee had previously maintained the MPR at 26.5 per cent in May and July after reducing it by 50 basis points from 27 per cent in February.
According to the CBN, the latest adjustment should not be interpreted as a complete change in its monetary policy stance, but as an operational reset designed to improve the effectiveness of monetary policy and support the transition towards an inflation-targeting framework.
The MPC also changed the asymmetric corridor around the MPR from +50/-450 basis points to +50/-300 basis points.
The adjustment is intended, among other things, to discourage banks from leaving excess funds idle with the CBN and encourage greater lending to businesses and other productive sectors.
However, the CBN retained the Cash Reserve Ratio (CRR) for commercial banks at 45 per cent, while the CRR for merchant banks remained at 16 per cent. The CRR on non-TSA public-sector deposits was also retained at 75 per cent.
The interest rate reduction comes against the backdrop of easing inflationary pressure in Nigeria.
According to figures cited in the report, headline inflation stood at 15.39 per cent in August, compared with 15.43 per cent in July, 15.91 per cent in June and 15.93 per cent in May.
The moderation in inflation has strengthened the argument for a less restrictive monetary policy environment.
Yusuf said the decision could help rebalance monetary policy towards economic growth, investment and recovery while maintaining attention on price and financial-system stability.
He noted that the previous 26.5 per cent MPR had become increasingly misaligned with inflation and prevailing money-market rates, weakening the signalling role of the policy rate.
According to him, bringing the MPR down to 23 per cent could help reduce the cost of capital, improve business cash flow and encourage investment in sectors such as manufacturing, agriculture, construction and logistics.
One of the biggest questions following the CBN’s decision is whether commercial banks will immediately reduce their lending rates.
Yusuf said the success of the policy would ultimately depend on how effectively the rate cut is transmitted to borrowers.
He argued that banks should progressively adjust the pricing of new and existing credit facilities to reflect the new monetary policy environment.
Without such transmission, he warned, the impact of the rate cut on investment, production and job creation could remain limited.
Prof Uche Uwaleke, Director of the Institute of Capital Market Studies and President of the Capital Market Academics of Nigeria, supported the decision, saying the reduction was justified by moderating inflation, exchange-rate stability, improved foreign-exchange market liquidity and growth in external reserves.
He also linked the development to the recently signed Memorandum of Understanding between the Minister of Finance and the CBN Governor aimed at improving fiscal and monetary policy coordination.
Economist Dr Marcel Okeke, however, expressed concern about the scale of the reduction.
Okeke described the 350-basis-point cut as unprecedented and questioned whether it would automatically result in cheaper loans for businesses and consumers.
He also raised questions about the possible relationship between the rate decision and the recent fiscal-monetary policy coordination agreement between the Ministry of Finance and the CBN.
According to him, monetary easing alone cannot guarantee greater access to credit because banks consider several factors beyond interest rates when deciding whether to lend.
Okeke also argued that Nigeria’s wider business environment must improve for lower interest rates to translate into stronger investment and economic activity.
Analysts at Cowry Asset Management described the decision as a notable shift in the CBN’s monetary policy direction.
They said the 350-basis-point reduction represents a significant easing of financial conditions as the central bank attempts to balance price stability with the need to support economic activity.
Former Securities and Exchange Commission (SEC) Director-General Suleyman A. Ndanusa also said the decision could potentially reduce borrowing costs, ease government debt-service pressures and give businesses and households greater financial breathing space.
However, he cautioned that the impact may not be as immediate as the headline rate reduction suggests.
Ndanusa pointed out that the CBN had retained relatively high CRR requirements for banks, meaning that while the central bank has reduced the benchmark price of money, significant liquidity restrictions remain.
He therefore argued that cheaper credit may not reach businesses and consumers automatically or immediately.
The latest CBN decision could influence several areas of the Nigerian economy, particularly borrowing, investment, business expansion and financial-market conditions.
For businesses, a reduction in the benchmark interest rate could eventually lower the cost of accessing credit, potentially improving cash flow and making some investments more viable.
For households and consumers, the effect will depend largely on whether commercial banks reduce lending rates and expand access to credit.
For the government, lower interest rates could potentially reduce the cost of domestic borrowing and debt servicing over time.
However, the continued high CRR requirements and other lending conditions mean the impact of the rate cut will depend heavily on how banks respond.
The latest decision therefore marks a significant development in Nigeria’s monetary policy, but its broader economic impact will become clearer as financial institutions adjust their lending rates and businesses respond to changing financing conditions.