
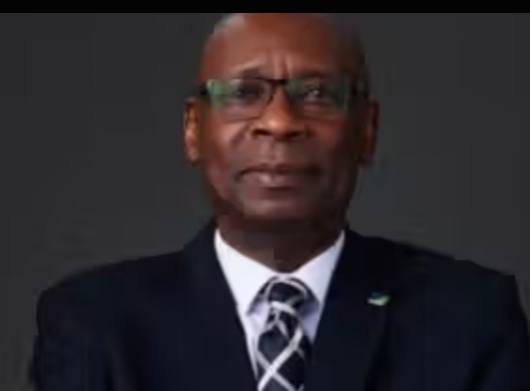
Mustafa Chike-Obi, former chairman of Fidelity Bank, has questioned the economic benefits of Nigeria’s large foreign exchange reserves, arguing that holding between $52 billion and $53 billion in reserves comes at an annual cost exceeding $10 billion.
Chike-Obi made the remarks on Thursday during an episode of Policy Without Politics, a podcast he hosts with Ken Ikpe, where economic and public policy issues are discussed.
According to the former bank chairman, the size of a country’s foreign reserves should not, on its own, be used to determine whether its economy is performing well or whether citizens are better off. He argued that the cost of maintaining such reserves must also be considered when assessing the country’s economic position.
Foreign exchange reserves are assets held by a country’s monetary authorities, usually in foreign currencies and other internationally recognised instruments. They serve as a financial buffer that can help a country meet external obligations, support confidence in its currency and manage pressure on the foreign exchange market.
For Nigeria, which depends significantly on foreign exchange earnings from crude oil exports and other international transactions, reserves are particularly important for managing external shocks and meeting the country’s foreign currency needs.
However, Chike-Obi’s comments highlight a broader economic debate about the balance between maintaining substantial reserves and deploying available resources to support investment, production and economic growth.
Nigeria’s foreign reserves can help the Central Bank of Nigeria (CBN) manage exchange-rate pressures, meet foreign currency obligations and strengthen confidence among international investors, lenders and trading partners.
A healthy reserve position can also provide protection when oil prices fall, foreign investment declines or external financing becomes more difficult to obtain.
Nevertheless, the benefits of holding reserves depend on several factors, including how the assets are invested, the returns they generate, the cost of obtaining or maintaining them and the country’s immediate economic needs.
Chike-Obi’s argument suggests that policymakers should look beyond the headline reserve figure and examine the financial implications of maintaining the funds.
His estimate that sustaining reserves of $52 billion to $53 billion costs Nigeria more than $10 billion annually raises questions about the nature of the expenses included in that calculation.
The figure would need to be assessed against the returns earned on reserve assets, the cost of any associated borrowing or sterilisation operations, and the methodology used to arrive at the estimate. The reported remarks did not provide a detailed breakdown of these costs.
The debate is particularly relevant as Nigerians continue to assess the effects of economic policies on inflation, purchasing power, employment, business operations and the cost of living.
Although strong foreign reserves can improve a country’s ability to withstand external shocks, they do not automatically guarantee lower food prices, cheaper transport, higher wages or improved living standards.
Those outcomes also depend on domestic production, fiscal management, monetary policy, infrastructure, productivity and the effectiveness of government spending.
A country may hold substantial foreign assets while households and businesses continue to face economic difficulties. Equally, reserves that are too low can expose an economy to exchange-rate instability, difficulties financing imports and reduced confidence in its ability to meet international obligations.
The policy challenge, therefore, is to maintain sufficient external buffers without imposing unnecessary costs or neglecting other economic priorities.
Chike-Obi’s comments bring attention to the need for greater clarity about the costs and benefits of Nigeria’s reserve-management strategy.
Beyond announcing the amount held in reserves, economic authorities must consider whether the funds are generating appropriate returns, how much it costs to maintain them and how the reserve position contributes to broader economic stability.
The distinction between gross and net reserves is also important. Gross reserves represent the total eligible reserve assets, while net reserves account for relevant foreign currency liabilities and other adjustments under the methodology used. The two figures can provide different pictures of a country’s available external financial strength.
For investors and businesses, reserve adequacy is an important indicator of economic resilience. For ordinary Nigerians, however, the ultimate test of economic policy also includes whether stability in the foreign exchange market translates into more predictable prices, stronger businesses and better employment opportunities.
Chike-Obi’s central argument is that Nigeria’s economic performance should not be judged solely by the size of its foreign reserves. The costs of maintaining those reserves and the tangible benefits they deliver to the wider economy must also form part of the assessment.