
ABUJA: The Presidency has identified financial inclusion as a critical requirement for achieving Nigeria’s ambitious $1 trillion economy target by 2030, saying the country must bring millions of economically active citizens, particularly women, young people and small business owners, into the formal financial system.
The Federal Government said achieving the economic target would require more than conventional economic reforms, stressing the need to formalise grassroots economic activities and expand access to financial services for individuals and businesses currently operating outside the formal financial system.
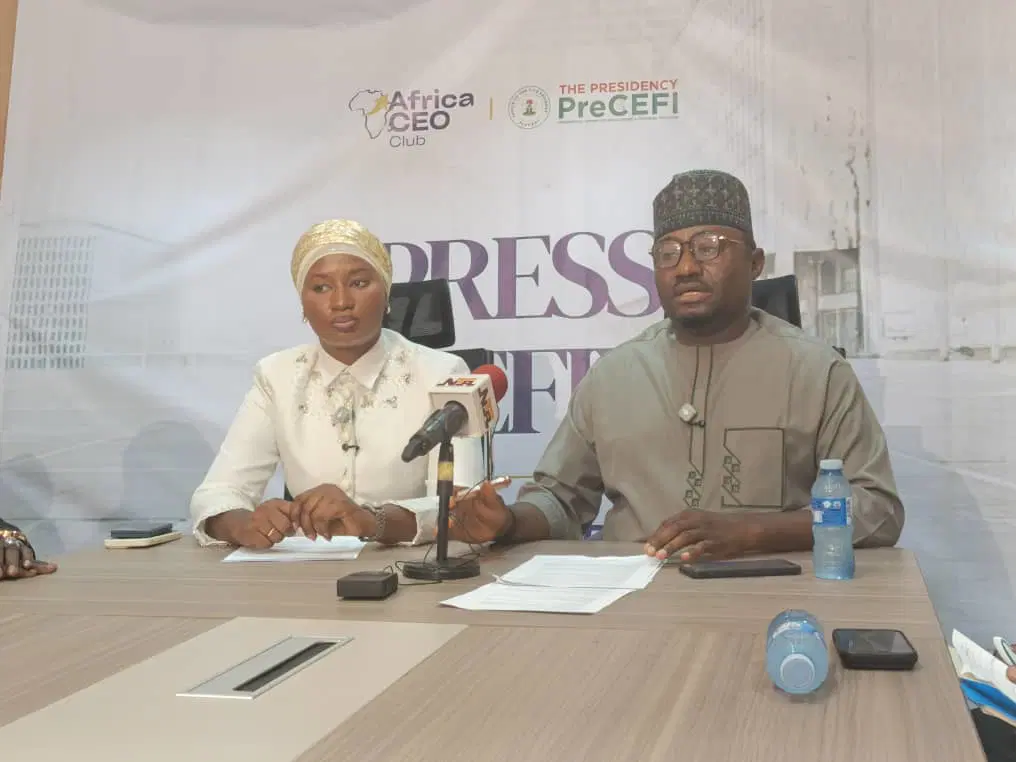
Technical Adviser to President Bola Tinubu on Economic and Financial Inclusion, Dr Nurudeen Abubakar Zauro, made this known in Abuja while announcing a strategic partnership between the Presidential Committee on Economic and Financial Inclusion (PreCEFI) and the Africa CEO Club ahead of the Africa Blueprint Summit 2.0 scheduled for December 3, 2026.
Zauro explained that financial inclusion must extend beyond opening bank accounts to providing Nigerians with access to credit facilities, savings, insurance, pensions, investment opportunities and wider domestic and international markets.
According to him, Nigeria’s ambition of building a $1 trillion economy cannot be fully realised while millions of women, youths, rural households and small business owners remain excluded from formal financial services and productive economic opportunities.
He described financial inclusion as a major driver of economic growth, enterprise development, job creation and national prosperity.
“This work sits at the heart of the Federal Government’s economic agenda. Millions of our citizens, many of them women, young people, rural households and small business owners, still operate outside the formal financial system.
They lack access to savings, credit, insurance and pensions. If we are to build a one trillion dollar economy, we cannot leave them behind. Inclusion is not charity. It is growth,” Zauro stated.
The presidential aide said the Presidential Committee on Economic and Financial Inclusion, under the leadership of Vice President Kashim Shettima, was coordinating government institutions, financial regulators and private-sector stakeholders to expand access to financial services across the country.
He identified digital public infrastructure, consumer protection and simplified onboarding procedures as essential measures for removing barriers that prevent many Nigerians from accessing formal financial services.
Zauro particularly highlighted challenges associated with inadequate banking facilities and difficulties obtaining formal identification, noting that addressing these obstacles would help bring more economically active citizens into the financial system.
He stressed that financial inclusion must produce measurable economic benefits rather than merely increase the number of people with bank accounts.
According to him, the ultimate objective is to enable small businesses to access loans, expand operations, employ more workers and eventually participate in cross-border trade.
“Opening an account is the first step, not the last. True inclusion means that the small business can borrow, grow, hire and one day sell across borders,” he said.
Explaining the partnership with the Africa CEO Club, Zauro said the collaboration was designed to bridge the gap between financial inclusion and enterprise development.
He said the initiative would connect entrepreneurs with financial institutions, regulatory authorities and other organisations capable of providing funding, business support and access to markets.
The partnership will feature prominently at the Africa Blueprint Summit 2.0, scheduled to take place on December 3, 2026, at the Congress Hall of Transcorp Hilton, Abuja.
The summit, themed “The Builders’ Mandate: From Blueprint to Build,” is expected to attract approximately 1,000 business leaders, investors, policymakers and regulators from across Africa and the diaspora.
Participants are expected to develop a Builders’ Mandate containing 10 priority policy interventions for governments and 10 corresponding commitments from the private sector to promote economic growth, investment and sustainable enterprise development.
Zauro said PreCEFI would ensure that the concerns of micro, small and medium enterprises (MSMEs), particularly women-owned and youth-led businesses, receive adequate attention during discussions on access to capital, regulatory reforms and enterprise development.
In her remarks, President of the Africa CEO Club, Dr Fatoumatta Gaye, said the summit would address what she described as Africa’s institutional deficit, particularly the inability of many businesses to survive beyond their founders.
Gaye expressed concern that several African enterprises lacked effective succession plans, professional management structures and institutional frameworks capable of ensuring continuity across generations.
She argued that Africa had no shortage of talented entrepreneurs but needed stronger institutions capable of transforming businesses into sustainable organisations that could survive for decades.
Africa does not lack brilliant founders. What we lack are institutions that outlive them. Too many of our businesses rise with one person and fall with that same person. Too few become 50-year companies, she said.
Gaye disclosed that the Builders’ Mandate would be endorsed by participating business leaders and presented to governments, while the Africa CEO Club would monitor and publicly report progress on its implementation throughout 2027.
Reflecting on the maiden edition of the summit, held on November 27, 2025, at the Afreximbank African Trade Centre in Abuja, Gaye said the event attracted more than 600 business and policy leaders and over 60 media organisations.
She disclosed that the inaugural summit facilitated business transactions through its Deal Room and secured $5 million for the development of the Africa CEO Club’s digital ecosystem.
According to her, the organisation has since established its headquarters in Abuja, recruited more than 60 employees, expanded its membership and strengthened partnerships with public- and private-sector institutions.
She also announced that the organisation’s digital platform, designed to connect business leaders and enterprises across Africa, would be officially launched on March 18, 2027.
The December summit will feature several discussions on business financing, investment, policy reforms, succession planning and institutional development.
The first panel, titled “Capital That Builds,” will examine sustainable financing and long-term capital for business expansion.
Expected speakers include Managing Director of the Asset Management Corporation of Nigeria (AMCON), Gbenga Alade; Managing Director of the Bank of Agriculture, Ayo Sotinrin; Chief Executive Officer of Moniepoint, Tosin Eniolorunda; and Director-General of the Governance Delivery Unit, Dr Olusiji Aina.
Other activities will include a founders’ conversation, live podcast, investment Deal Room and an exhibition providing MSMEs and start-ups with opportunities to connect with investors, buyers and development partners.
Gaye said the event would also be livestreamed to an anticipated audience of at least three million people.
She described the partnership with PreCEFI as strategic, noting that financial inclusion was essential to building sustainable businesses and expanding economic opportunities across Africa.
She cited the need to support women traders seeking access to banking services, young entrepreneurs looking for loans and small-scale manufacturers seeking opportunities to enter export markets.
Gaye urged African business owners and investors to participate in the summit, stressing that stronger private-sector engagement was necessary to influence policies relating to taxation, access to finance and investment.
She further announced that early-bird registration would close on November 15, 2026, while groups registering more than three participants would enjoy a 20 per cent discount.
The Federal Government’s renewed emphasis on financial inclusion underscores the importance of integrating informal businesses and underserved populations into Nigeria’s formal economy.
For millions of small business owners, traders, farmers and young entrepreneurs, access to affordable credit, insurance, savings and investment opportunities could provide the financial foundation needed to expand operations, create jobs and improve productivity.
However, the success of the initiative will depend on how effectively the government and financial institutions translate policy commitments into accessible and affordable financial services, particularly for people and businesses in rural communities.
As Nigeria pursues its $1 trillion GDP ambition by 2030, the challenge will be ensuring that economic growth creates opportunities beyond large corporations and established businesses, extending to ordinary Nigerians who form the backbone of the country’s grassroots economy.
RapidoSpace News | Business and Economy